
Interchange
Generally paid through the payment system to the card issuer. It varies by card type, merchant category and how a payment is submitted.
Compare the full cost of your account, not just the headline percentage.
Generally paid through the payment system to the card issuer. It varies by card type, merchant category and how a payment is submitted.

Card-network charges contribute to the total. Ask how they appear on your statement and whether a quoted rate includes them.

The provider’s charge for processing services: a percentage, a per-transaction amount, or both.

Account minimums, gateway or software charges, hardware, PCI-related charges and dispute fees may apply. Review your own agreement.
Interchange is passed through separately from the provider’s markup. Network fees and other charges still contribute to the total, which varies with your transaction mix.
Core processing costs are generally bundled into a stated rate for a transaction type. In-person, online and keyed payments may have different rates, with additional fees outside them.
These are models to compare, not a claim that every Payline relationship offers both. Review a quote and agreement for your business; calculator results are estimates, not guaranteed costs.
Monthly charges spread across fewer transactions can raise your effective rate. Higher volume alone does not guarantee a lower total bill.
A per-transaction fee takes a larger share of a small sale. Compare quotes using your typical ticket size and transaction count.
In-person, online and manually keyed transactions have different cost profiles. Your card mix and cross-border activity also matter.
Business activity, fulfillment timing and underwriting requirements affect the account and tools available to you.
Compare the channels you need: in-person payments, online payments, recurring billing or a virtual terminal and gateway.
Use a representative month’s card-sales volume and transaction count. Check other months for seasonality and annual charges.
Separate interchange, network charges and provider markup. Include relevant gateway, account and equipment bills in the comparison.
Divide fees in your chosen scope by matching processed card-sales volume, then multiply by 100. Treat refunds and credits consistently.
Use the same volume, ticket size and channels. Review funding, cancellation terms and equipment commitments alongside the projected total.
Reserve holdbacks and chargeback principal affect cash availability but are not processing fees. Track them separately to keep the comparison useful.
Choose from modern, secure terminals that fit your workflow
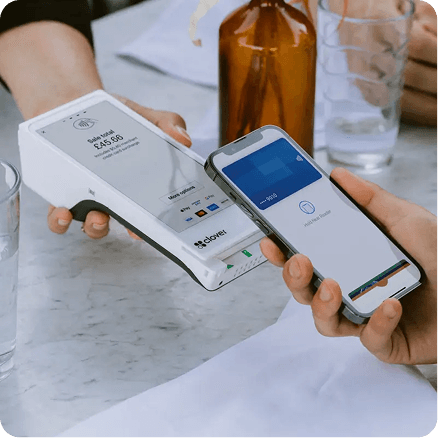
All-in-one, handheld terminal with built-in printer, barcode scanner, and Wi-Fi — perfect for mobile checkout and small counters.
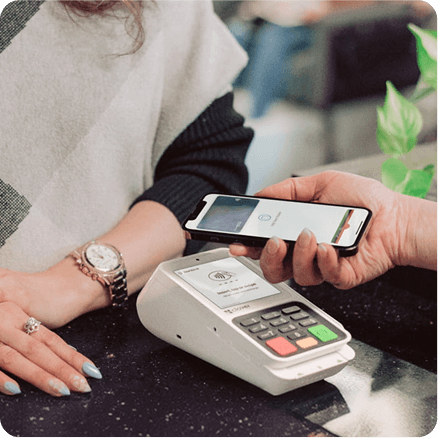
Simple, reliable countertop terminal with chip, swipe, and contactless payments. Ideal for traditional checkout setups.
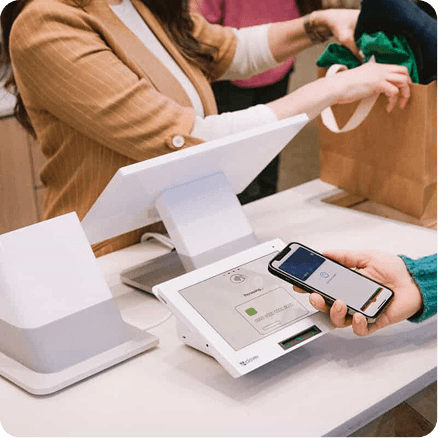
Offers a full touchscreen POS experience with inventory, reporting, staff tools, and built-in receipt printer — best for busy counters.
Your processing fees divided by the matching card-sales volume, expressed as a percentage. It is a retrospective comparison measure, not necessarily your contracted rate. Use the same fee categories and period when comparing providers.
No. Per-transaction charges, monthly fees, card mix and services outside the advertised rate can change the total. Compare a representative statement and the whole agreement, including any conditions attached to the offer.
Interchange is a component of card-payment costs generally paid through the payment system to the card issuer. It varies with factors such as card type and transaction characteristics.
It is the provider’s markup within the pricing arrangement. Under interchange-plus pricing it is identified separately from interchange, though other charges may also apply.
Check the current offer and your agreement for any applicable PCI-related charges and requirements. A statement about one plan should not be assumed to apply to every processing relationship.
Terms depend on the agreement and selected services. Review the processing arrangement and any separate equipment or service commitments before signing.
Funding timing follows the approved account’s terms and may be affected by transaction submission, banking schedules or review. Confirm the schedule and any associated charges for your offer.
Costs depend on the equipment and purchase, rental or other arrangement offered. Review the full payment schedule and any separate obligations.
A calculator provides an estimate based on its assumptions and inputs. Actual costs depend on your transactions, agreement and applicable charges.
“It is user-friendly. Payline deposits in our bank account is an advantage. The additional security codes provide a layer of protection.”
“Payline helps our accounting team balance financial reports by managing financial transactions such as payments and refunds. Essentially, it's a straightforward method to manage all of our purchases and sales within a single app.”