
Access to Multiple Processors
Compare providers suited to your industry, business model and processing history, instead of trying to fit every merchant into one program.
Declined by another processor—or concerned about sudden account restrictions? Payline helps high-risk businesses navigate underwriting and find payment processing options suited to their industry, business model, and risk profile.
Processors may classify a business as high risk because of its industry, transaction size, recurring billing, chargeback history or fulfillment timeline.
Payline reviews your business model and processing needs to identify suitable options across multiple processing partners. Provider selection matters: each program has its own eligibility rules, terms and supported activities.
We help prepare documentation and coordinate underwriting. The acquiring bank and processing program determine approval, reserves, limits and funding conditions; a gateway alone does not establish eligibility.
High-risk merchant accounts are placed through multiple providers and are not sponsored by Fiserv or its related sponsor banks.
Provider fit, application support and transparent processing options.
Compare providers suited to your industry, business model and processing history, instead of trying to fit every merchant into one program.

Get help organizing documents, responding to underwriting questions and keeping your application moving, with one team coordinating the process.

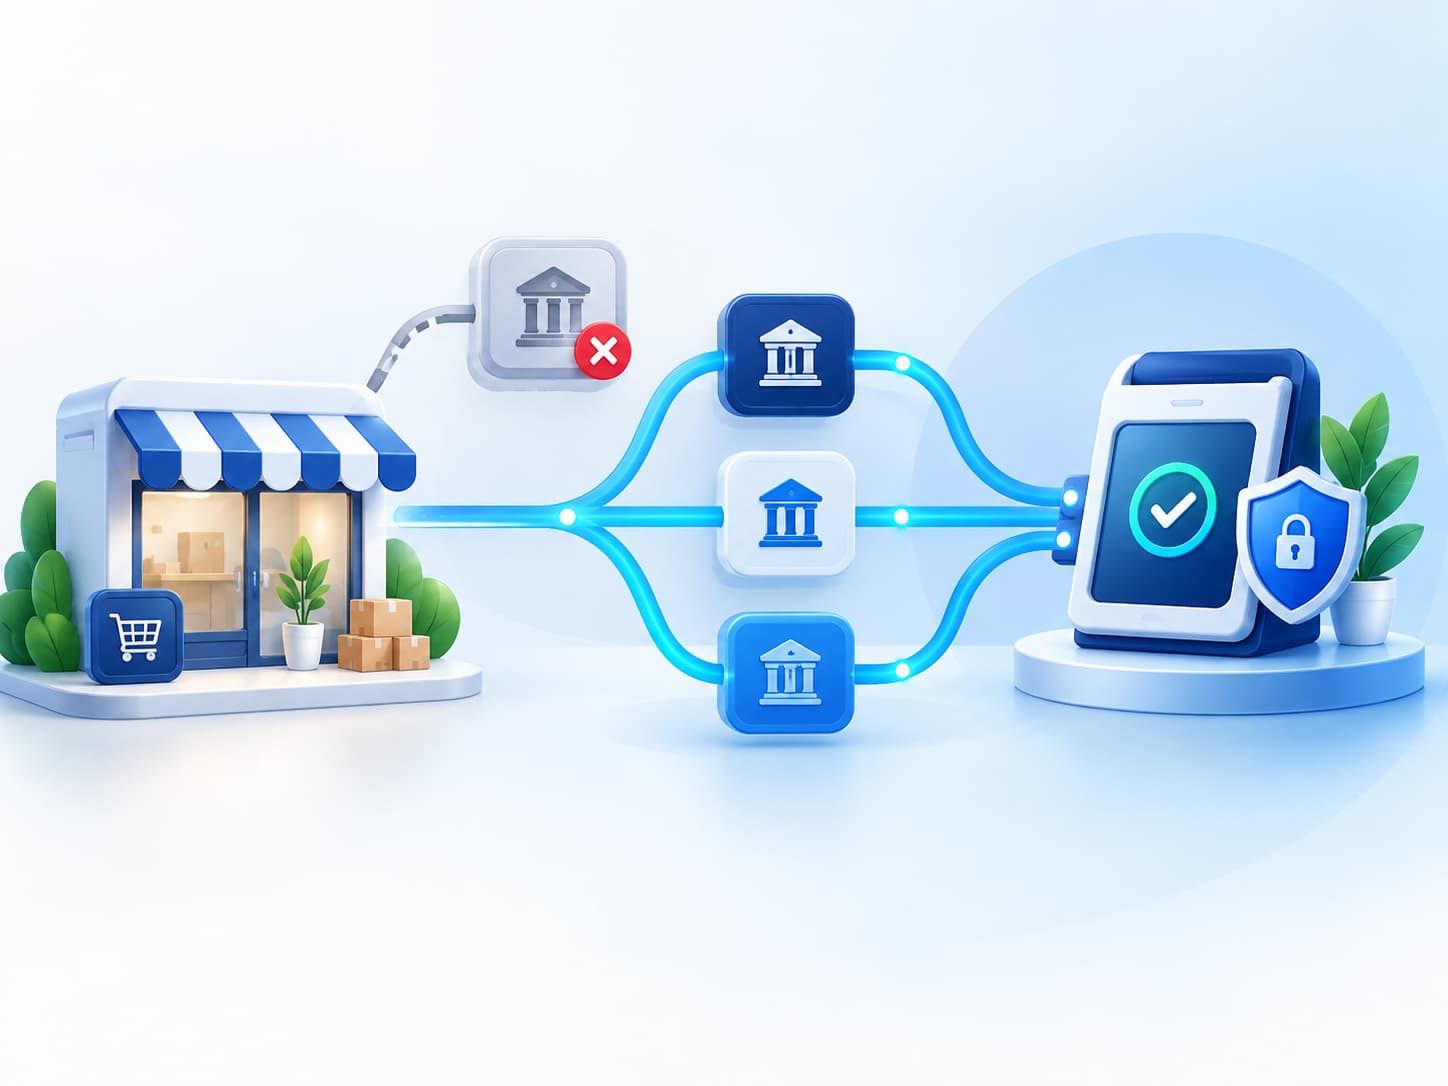
For eligible established businesses, explore fully disclosed, provider-approved account arrangements that support distinct processing needs and reduce reliance on one relationship.

Access supported chargeback alerts, dispute-management tools and fraud controls to help monitor account health. Availability depends on your provider and setup.
A decline or account closure does not necessarily leave your business without options. Payline helps evaluate alternative processing relationships based on your industry, risk profile and processing history.
We review your business, prepare documentation and coordinate with suitable providers. Disclose prior account issues accurately and bring the notice and recent processing statements. Approval depends on underwriting; a new account does not remove prior obligations.
Merchant account applications · Evaluating Stripe alternatives
Hard-to-place does not mean impossible. Payline helps legal, compliant businesses across complex and highly scrutinized industries find appropriate payment processing options.

Options for eligible supplement and nutraceutical businesses, subject to product, claims, fulfillment and billing review.

Review recurring billing, customer authorization, renewal disclosures and cancellation practices for eligible subscription businesses.

Specialized underwriting for compliant multilevel marketing and direct-sales organizations with recurring billing or complex distributor models.

Processing options for qualified coaching programs, online education, high-ticket courses, and other digital-product businesses.

Specialized payment processing for properly licensed firearms, tactical-products, tobacco, and related businesses operating in accordance with applicable laws and provider requirements.

Discreet payment processing options for legal and compliant adult-content, dating, and related online businesses.

Payment processing for qualified online gaming businesses requiring specialized underwriting, fraud controls, and dispute management.

Merchant account options for compliant telemedicine and virtual healthcare businesses, including companies using recurring or online billing.

Payment processing for qualified dropshipping businesses managing extended delivery times, fulfillment complexity, and increased dispute exposure.

Online payment processing for eCommerce businesses whose products, transaction patterns, growth, or operating models require specialized underwriting.

Options for eligible travel agencies and tourism businesses, with review of deposits, future delivery, refunds and seasonal volume.
“Other providers treated our business like a problem before understanding how we operated. Payline evaluated our actual processing history and business model, matched us with an appropriate provider, and helped us get through the approval process.”
Rebeca C.“We had been declined by another processor because of our industry. Payline took the time to understand our business, helped us organize the required documentation, and kept us informed throughout underwriting. The difference was having a team that knew how to navigate a complicated approval.”
Arindam B.“Their quick service and easy to get a hold of. They also have their own gateway with an API to access it.”
Stan T.“Chargebacks and recurring billing made it difficult to find a provider that understood our business. Payline helped us find the right processing relationship and gave us access to tools that made it easier to monitor disputes and protect the health of our account.”
Verified User“Payline makes transactions such as payments, refunds, and helps our accounting team reconcile financial reports. Basically, it is an easy way to track our purchases and sales in one app.”
Verified User“Buffy, out account representative. She is just AMAZING. Always gets back to us on time and is very helpful! I will not go back to any other merchant service provider. Customer service and clarity is what every business needs and looks for. With Payline you are guaranteed to have all that, We are very happy with Payline.”
Verified User“Our rep, Tiffany, is the best. She is always quick to respond and help with any situations that we have. We also like the next day deposit availability.”
Verified User“Payline managed the application and communicated directly with underwriting when additional information was requested. Instead of trying to interpret every request ourselves, we had an experienced team helping us respond and keep the process moving.”
Verified UserPayline helps eligible businesses evaluate more than one fully disclosed, provider-approved processing relationship. Each provider decides eligibility and terms.
A MID identifies an account; it does not provide automatic routing or backup. Confirm permitted activity, limits, gateway compatibility and operating responsibilities for each relationship.
For high-ticket or future-delivery sales, bring typical and maximum charges, volume and seasonal peaks, delivery dates, cancellation/refund terms and fulfillment evidence. Include advance payments and requested financial or processing records. Requirements vary by provider.
A high-risk merchant account is a payment processing account for businesses that processors or sponsor banks consider more likely to experience chargebacks, fraud, regulatory scrutiny, delayed fulfillment, or other financial risks. A business may also be classified as high risk because of its industry or billing model.
Applications may be declined because of the business category, products sold, processing history, chargebacks, website compliance, licensing, expected volume, financial condition, or a mismatch with the provider’s underwriting guidelines. A decline from one provider does not necessarily mean every provider will make the same decision.
Payline cannot guarantee merchant account approval. Every application is subject to underwriting. Payline identifies appropriate providers, prepares the application, manages underwriting communication, and helps resolve requests for additional information.
Timing depends on the business and the completeness of the application. Straightforward applications may be reviewed relatively quickly, while businesses requiring additional financial, licensing, product, or processing-history documentation can take longer.
High-risk merchant accounts commonly have higher processing costs than standard-risk accounts because the provider assumes additional financial and operational exposure. Pricing may be affected by the industry, chargebacks, transaction size, processing volume, financial condition, and whether a reserve is required.
A rolling reserve is a portion of processed funds temporarily held to cover potential chargebacks, refunds or other losses. Not every account requires one. Review the amount, release schedule and conditions in the provider’s offer. See how processing reserves work and the high-risk payments strategy guide.
Potentially. Payline can review why the account was closed, assess the business and processing history, and determine whether another provider may consider the application. Approval and timing depend on the circumstances.
Yes, in appropriate situations. Multiple merchant accounts may support different brands, products, sales channels, regions, or processing needs when they are fully disclosed and approved. Payline can help qualified businesses establish a compliant multiple-MID or multiple-processor strategy.
The acquiring or sponsor-bank relationship and the processor’s program both affect which businesses can be supported. Opening a business checking account does not itself approve card processing. Evaluate the actual provider’s eligibility rules for your products, sales channels, fulfillment and processing history; a familiar bank name is not a guarantee of acceptance. Payline helps identify suitable providers and coordinate underwriting.
Review the full written pricing, funding schedule, reserve and release conditions, processing limits, dispute fees, contract term and cancellation terms. Confirm gateway compatibility and who handles support and account reviews. Higher-risk accounts may have additional conditions, but no single fee, reserve percentage or funding timetable applies to every business.
Use a recognizable billing descriptor, clear refund and fulfillment policies, and supported fraud controls. Monitor disputes and refunds, respond to document requests, and notify your provider before material changes to products, billing models, sales channels or expected volume. Follow the limits and monitoring requirements for your specific account rather than relying on a universal chargeback threshold.
Individually underwritten providers may consider eligible businesses Stripe declines. Payline helps evaluate Stripe alternatives; changing providers does not resolve legal or compliance issues.
Understand the reason and compare providers that fit your actual business activity.
Gather the closure notice, statements, dispute and refund records. A new account does not guarantee approval or release existing reserves.
Bring accurate business, ownership, banking, product and processing information. Your provider may request more. Confirm payment methods and gateway compatibility alongside account eligibility.